19.11.2026
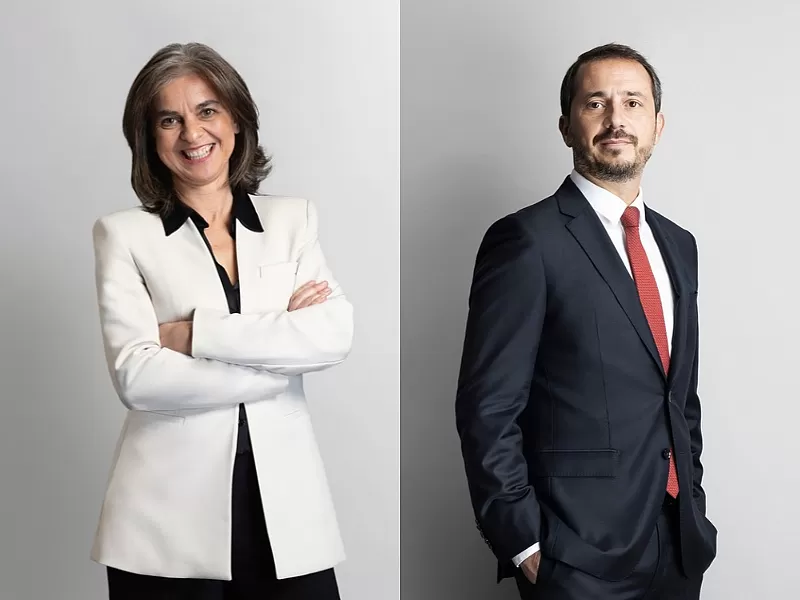
Diogo Mafra and Maria do Carmo Virtuoso write about W&I insurance in real estate transactions
Warranty & Indemnity insurance, or W&I insurance, has become increasingly relevant in real estate transactions, particularly in managing the risk associated with representations and warranties given by sellers. This is the subject of the article “Reallocating Warranty Risk: The Role of W&I Insurance in Corporate Real Estate Deals”, written by Diogo Mafra and Maria do Carmo Virtuoso.
W&I insurance and risk management in real estate transactions
In corporate real estate transactions, sellers typically provide a set of representations and warranties, commonly referred to as R&W, which help define the parties’ responsibilities and reinforce the reliability of the information disclosed to the buyer.
A breach of those representations and warranties may give rise to claims for losses suffered after completion of the transaction. W&I insurance allows part of that risk to be transferred to an insurer, helping to limit the seller’s post-closing exposure and preserve the stability of the transaction.
Benefits of W&I insurance for sellers and buyers
For sellers, W&I insurance can facilitate a faster and more efficient exit, reducing the need to retain a significant portion of the purchase price in a guarantee account and limiting exposure to long-term indemnity obligations.
The transfer of risk to an insurer can also simplify the negotiation of traditionally sensitive matters, such as liability caps, deductibles and indemnity mechanisms.
For buyers, W&I insurance provides an additional layer of protection by allowing certain claims to be made against an insurer, rather than relying exclusively on the seller’s ability to respond to losses after the transaction. This can provide greater certainty of recovery for covered losses and contribute to greater confidence in pricing.
Synthetic W&I can facilitate more complex transactions
The article also focuses on synthetic warranties, which may be used where the seller is unwilling or unable to provide certain representations and warranties.
Under this model, coverage is structured around the risk the insurer is prepared to accept. The policy therefore takes on a central role in allocating transaction risk, with warranties shaped by the available information and the insurer’s underwriting process.
This approach can help make transactions viable that would otherwise be more difficult to complete under a conventional structure. However, coverage tends to focus on objectively verifiable matters, such as title, corporate status, material contracts, tax matters and licences.
Due diligence remains essential
Diogo Mafra and Maria do Carmo Virtuoso emphasise that W&I insurance does not replace due diligence or adequate disclosure.
The quality of the documentation and information made available remains critical to the insurer’s risk assessment and to the scope of coverage. In the case of synthetic warranties, this is particularly important, as each information gap may result in a corresponding coverage gap.
W&I insurance is therefore becoming an increasingly relevant tool in the structuring of real estate transactions, allowing for a more efficient allocation of risk between sellers, buyers and insurers and contributing to faster, safer and more competitive deals.
Read the article in Iberian Property (subscribers only).